By Vanderbiltreport Team | September 25, 2026
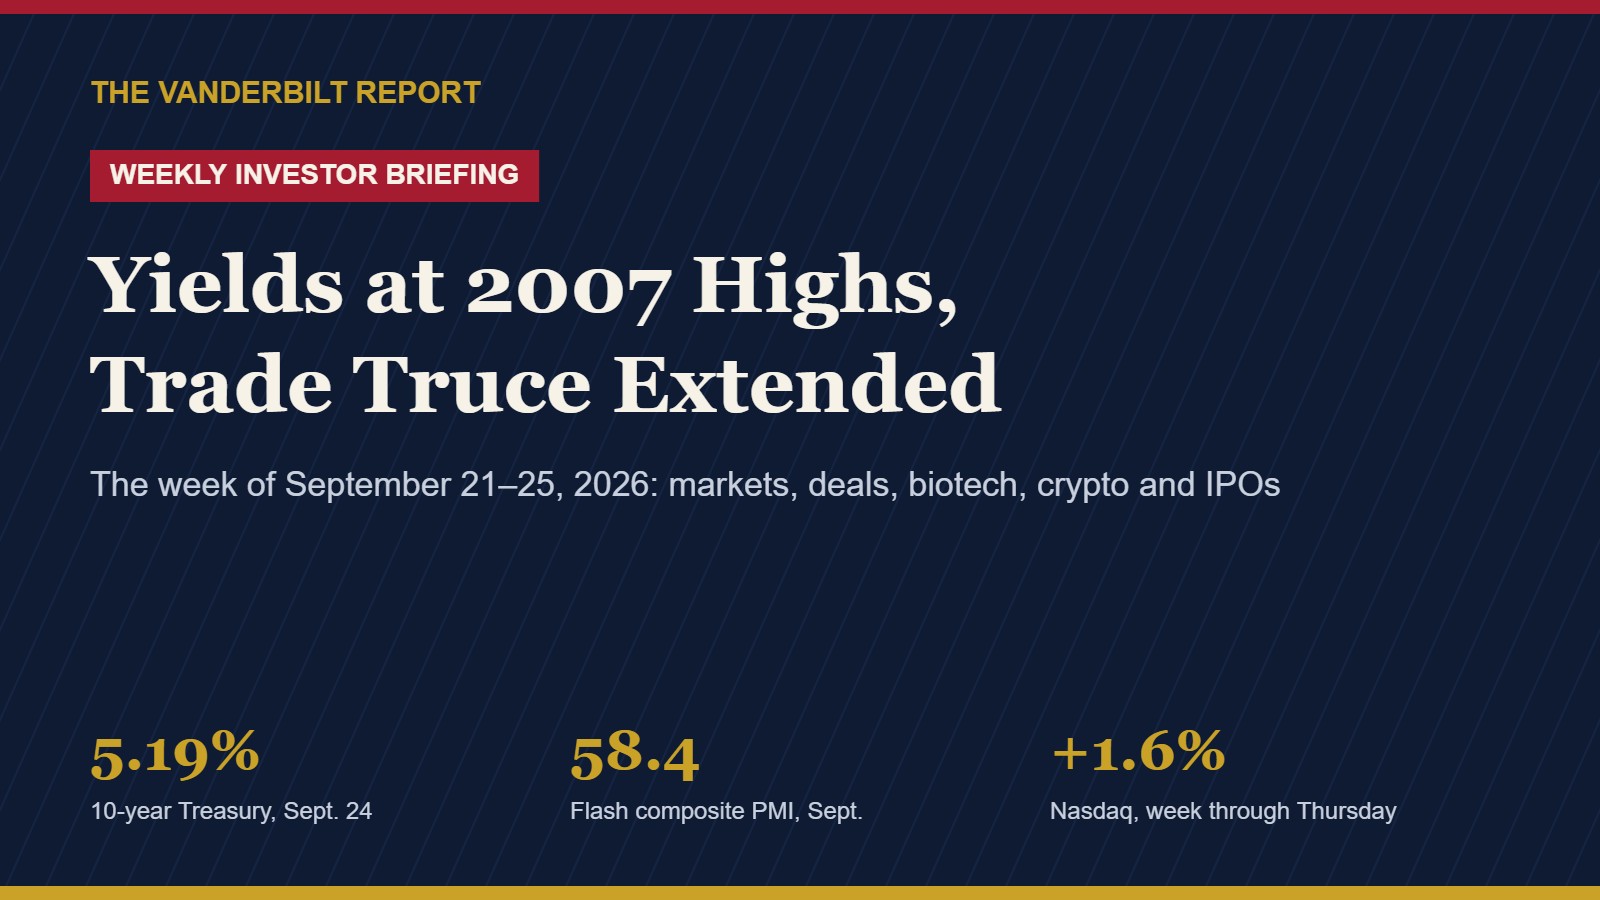
This weekly investor briefing covers the week of September 21–25, 2026. Treasury yields rose to levels last seen before the 2008 financial crisis. A surprisingly strong business survey pushed up expectations of another Federal Reserve rate increase. The United States and China agreed to extend their trade truce. Advanced Micro Devices joined the $1 trillion club, while Oracle and MGM Resorts fell on company-specific news. Bitcoin hit an eight-month high before giving back part of the gain.
How to read this briefing: Verified items come from official releases, regulators or government data. Reported items come from linked news coverage. Company statement means a company’s own description. Analysis and Commentary are Vanderbiltreport context or third-party views, not fact. Market figures are through the close on Thursday, September 24, and do not include Friday’s session.
The Week at a Glance
| Area | Development | Status |
|---|---|---|
| Markets | S&P 500 +0.7%, Nasdaq +1.6%, Dow −0.6% week-to-date through Thursday | Reported (AP) |
| Rates | 10-year Treasury yield about 5.19%, highest since 2007 | Reported |
| Economy | S&P Global flash composite PMI 58.4, highest since July 2021 | Reported |
| Fed | NY Fed’s Williams calls another hike this year “reasonable” | Reported |
| Trade | U.S. and China extend the Busan trade truce to January 10 | Reported |
| Tech | AMD tops $1 trillion; Oracle falls on data-center force majeure notice | Reported |
| Biotech | FDA panel backs GRAIL’s Galleri test; Viking reports VK2735 maintenance data | Verified |
| Crypto | Bitcoin hits eight-month high near $87,400, then pulls back to about $83,500 | Reported |
| M&A | Schneider Electric bids for Shelly Group; People Inc. drops $18B MGM bid | Verified / Reported |
| IPO | Oura launches Nasdaq IPO roadshow at a $15.62B fully diluted valuation target | Reported |
Markets: Stocks Split as Bond Yields Climb
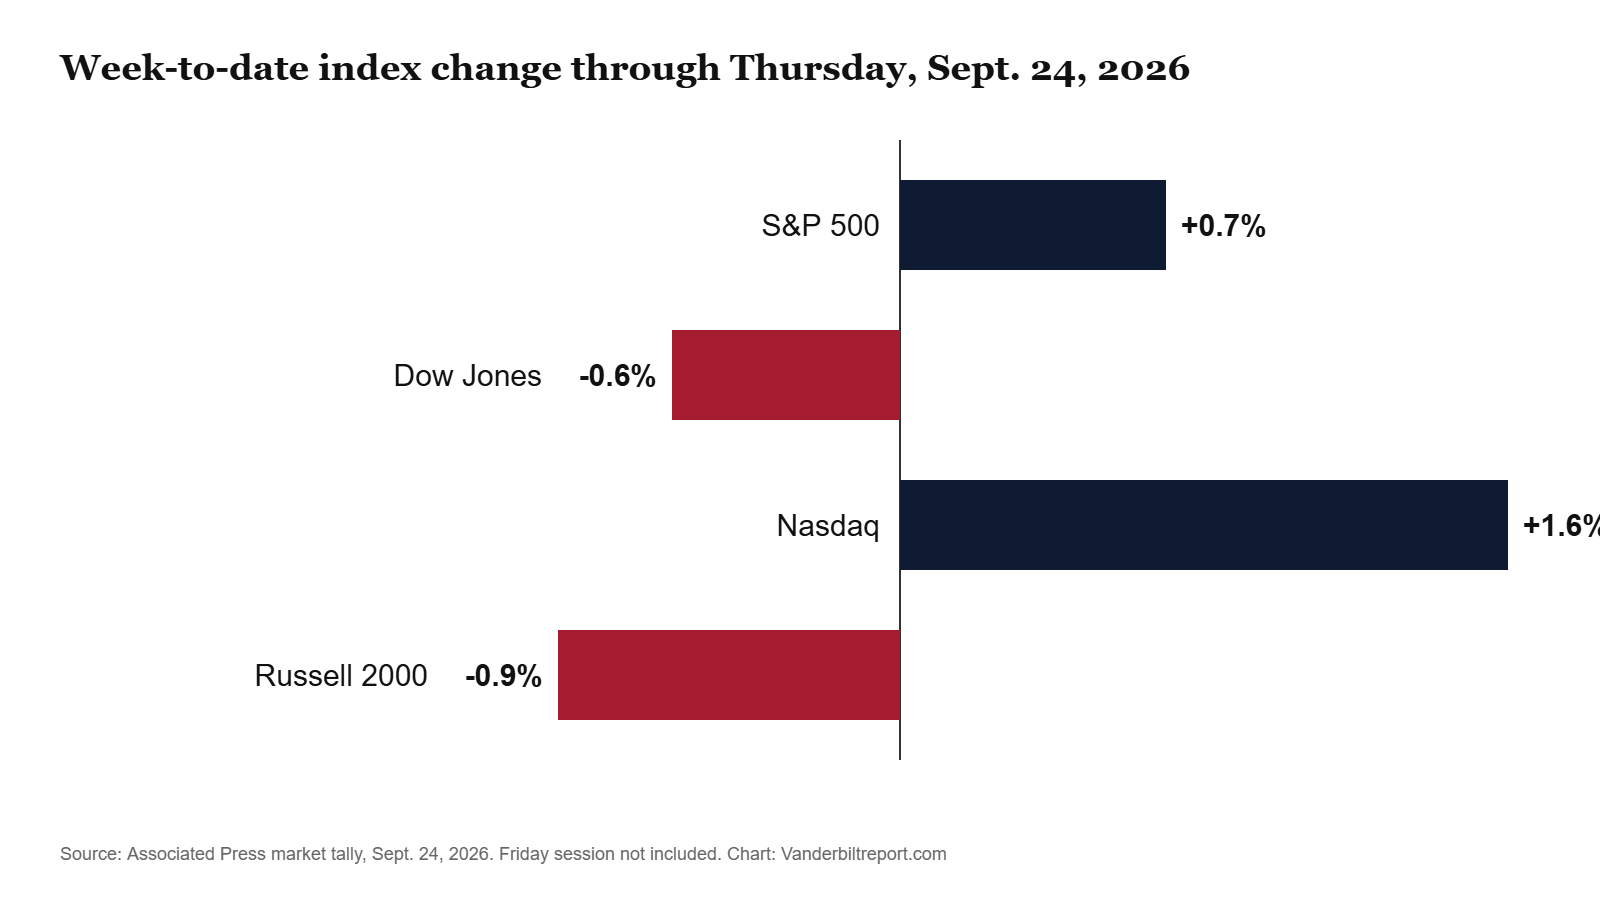
Reported. According to the Associated Press, Thursday’s closing levels were:
| Index | Close (Sept. 24) | Week to date | Year to date |
|---|---|---|---|
| S&P 500 | 7,704.13 | +0.7% | +12.5% |
| Dow Jones Industrial Average | 51,349.98 | −0.6% | +6.8% |
| Nasdaq Composite | 26,939.37 | +1.6% | +15.9% |
| Russell 2000 | 2,835.57 | −0.9% | +14.2% |
Reported. TheStreet reported that the 10-year Treasury yield rose about 7.8 basis points on Thursday to 5.192%, its highest since 2007. The 30-year yield reached 5.476%, its highest since 2004. WTI crude settled near $93 a barrel and Brent near $105. TheStreet linked the oil move partly to renewed Middle East tensions.
Economy and the Fed: Strong Data, Hawkish Signals
Reported. On September 23, S&P Global’s flash U.S. composite PMI for September came in at 58.4, well above the consensus of about 55.2 and the highest reading since July 2021, according to Tech Times. The input-prices index rose to 66.4, its highest since October 2022.
Reported. On September 24, New York Fed President John Williams said another rate increase before the end of 2026 is “a reasonable way of thinking about it,” Quartz reported. Futures pricing tracked by CME Group’s FedWatch tool showed roughly a 70%–75% probability of an October hike, according to reports this week. The Fed raised rates on September 17 (our coverage). Its next scheduled meeting is October 27–28.
Analysis. Strong activity data combined with rising input costs is the mix that tends to push policymakers toward tightening. Market-implied probabilities change daily and are not forecasts from the Fed.
Trade and World: U.S.–China Truce Extended
Reported. Chinese President Xi Jinping began a three-day visit to Washington this week. Al Jazeera reported that the two governments agreed to extend the “Busan Agreement” tariff truce from its November 10 expiry to January 10. Treasury Secretary Scott Bessent said the extension leaves time for “a bigger deal as opposed to just a series of smaller things.” Reports did not give detailed tariff or purchase figures for the extension.
Companies and Technology
AMD crosses $1 trillion
Reported. On September 21, Advanced Micro Devices (NASDAQ: AMD) topped a $1 trillion market value for the first time, Quartz reported. AMD’s most recent official figures are its second-quarter 2026 results. Our Company Behind the Ticker profile has more.
Amazon blocks Meta’s Muse AI agent
Reported. Amazon (NASDAQ: AMZN) began blocking Meta Platforms’ (NASDAQ: META) new Muse personal AI agent from shopping on Amazon.com, GeekWire reported. The block is a test case for how retailers will treat AI “agentic commerce.” Full story.
Oracle issues force majeure notice on Project Jupiter
Reported. On September 24, Oracle (NYSE: ORCL) issued a force majeure notice on Project Jupiter, a large New Mexico data-center development being built by Stack Infrastructure. Reports cited public opposition and permitting delays. The Motley Fool reported that the shares closed down 3.47% at $139.54 on heavy volume, and that Oracle’s credit default swaps hit a record high. TheStreet reported a larger intraday decline.
Costco reports fiscal Q4
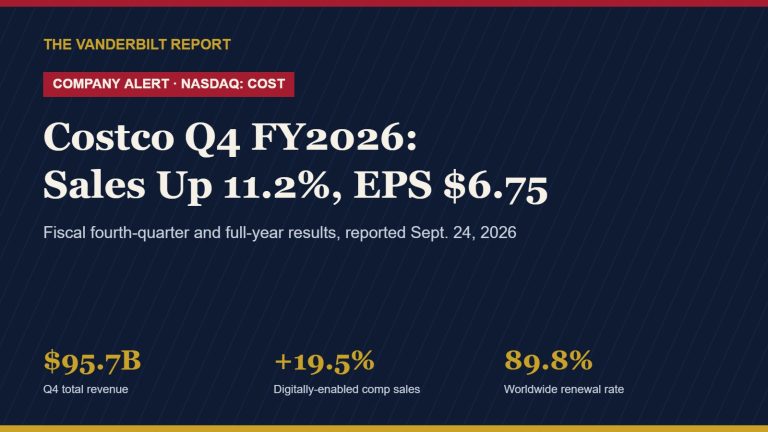
Verified. Costco reported fiscal fourth-quarter net sales up 11.2% and EPS of $6.75 after Thursday’s close. See this morning’s Costco Q4 earnings report for details.
Biotech and Health
FDA panel backs GRAIL’s Galleri test
Verified. On September 23, the FDA’s Molecular and Clinical Genetics Panel voted 10–0 that GRAIL’s (NASDAQ: GRAL) Galleri multi-cancer early detection test is safe. It voted 6–4 that there is reasonable assurance it is effective, and 7–2 with one abstention that its benefits outweigh its risks, according to GRAIL and CancerNetwork. The vote is a recommendation only, and the FDA makes the final decision. Our full coverage.
Viking’s VK2735 maintenance data
Verified. On September 22, Viking Therapeutics (NASDAQ: VKTX) reported topline maintenance-study results for its obesity drug VK2735. Patients kept up to 97% of their weight loss on every-other-week dosing and up to 90% on monthly dosing, compared with 61% after switching to placebo. These are company-reported topline data and have not been peer reviewed. Our full coverage.
Crypto: Eight-Month High, Then a Pullback
Reported. Bitcoin reached an intraday high of about $87,397 on September 21, its highest in eight months, Tech Times reported. The same report said spot bitcoin ETFs took in about $999 million in net inflows that day, the largest single-day total of 2026, and that a short squeeze added to the move. By Thursday, bitcoin was around $83,462 and ether around $2,647, Yahoo Finance reported. It attributed the pullback to rising expectations of a Fed rate hike. Both were still up about 11% over one week.
M&A: One Deal Announced, One Withdrawn
Schneider Electric bids for Shelly Group
Verified. On September 24, Schneider Electric (Euronext Paris: SU) announced a voluntary public takeover offer for Shelly Group SE at €70.00 per share in cash, valuing the company at about €1.2 billion, with the founders’ support (Schneider announcement). Our full coverage.
People Inc. withdraws $18 billion MGM Resorts bid
Reported. Barry Diller’s People Inc. withdrew its proposal to buy the rest of MGM Resorts International (NYSE: MGM) for $48.30 per share, a deal worth more than $18 billion, Reuters reported via Investing.com. People already owns about 27% of MGM. Diller said “we didn’t feel the mix was coming together in the way we had hoped.” MGM shares fell about 9% to 10% on September 24, according to Reuters and TheStreet.
IPOs: Oura Tests the Fall Window
Reported. Smart-ring maker Oura launched its IPO roadshow on September 21. It is offering 50 million shares at $40 to $44 each, to raise up to about $2.2 billion, and plans to list on the Nasdaq Global Select Market as OURA, Quartz reported. The target fully diluted valuation is about $15.62 billion. Yahoo Finance reported that Eli Lilly indicated interest in buying up to $100 million of shares. Final pricing and the first trading date had not been confirmed when this briefing was written.
Commentary and Analysis
This section is Vanderbiltreport analysis and third-party commentary, not verified fact.
- Rates matter more than earnings this week. The Nasdaq and S&P 500 held small weekly gains even as long-term yields rose to multi-decade highs. The Dow and Russell 2000 were negative for the week. That split shows the market treating large technology companies differently from rate-sensitive and smaller companies.
- AI infrastructure has limits outside the balance sheet. Oracle’s notice shows how permitting, local opposition and power supply can slow data-center projects. Commentators cited by The Motley Fool described this as a sign of pressure on AI capital-spending returns, not necessarily a turning point.
- Deal risk works in both directions. The withdrawal of the MGM bid erased the stock’s gains since June. That is a reminder that a proposed deal is not a completed deal.
What to Watch Next Week (September 26 – October 2)
Scheduled or officially documented events only. Dates and times can change, so check the linked source.
| Date | Event | Source |
|---|---|---|
| Sat., Sept. 26 | FDA target action date for Mirum Pharmaceuticals’ zilurgisertib (FOP) | Catalyst Watch |
| Tue., Sept. 29, 10:00 a.m. ET | Job Openings and Labor Turnover Survey (JOLTS), August | BLS schedule |
| Wed., Sept. 30, 8:30 a.m. ET | GDP (third estimate), Q2 2026, and corporate profits | BEA schedule |
| Wed., Sept. 30, 8:30 a.m. ET | Personal Income and Outlays, August, including PCE inflation | BEA schedule |
| Wed., Sept. 30 | Micron Technology (NASDAQ: MU) fiscal Q4 2026 results | Micron IR |
| Thu., Oct. 1, ~1:15 p.m. PT | Nike (NYSE: NKE) fiscal Q1 2027 results; call at 2:00 p.m. PT | Nike release |
| Fri., Oct. 2, 8:30 a.m. ET | Employment Situation (jobs report), September | BLS schedule |
| Week of Sept. 28 (reported) | Oura (OURA) expected Nasdaq trading debut, pending final pricing | Quartz |
Sources
- Associated Press via ABC News: How major US stock indexes fared Thursday, 9/24/2026
- TheStreet: Stock market today, Sept. 24, 2026
- Tech Times: US growth hits five-year high, PMI 58.4
- Quartz: NY Fed’s Williams on a year-end rate hike
- Al Jazeera: US, China agree to extend trade truce
- Quartz: AMD hits $1 trillion market cap
- GeekWire: Amazon blocks Meta’s Muse AI assistant
- The Motley Fool: Oracle issues force majeure notice on Project Jupiter
- GRAIL: FDA advisory committee votes
- Viking Therapeutics: VK2735 maintenance study topline results
- Tech Times: Record bitcoin ETF inflows and short squeeze
- Yahoo Finance: Bitcoin and ether prices, Sept. 24, 2026
- Schneider Electric: Voluntary public takeover offer for Shelly Group
- Reuters via Investing.com: MGM Resorts shares tumble after People withdraws bid
- Quartz: Oura kicks off IPO roadshow
- Yahoo Finance: Oura’s $15.6 billion IPO
Publisher Disclaimer: Vanderbiltreport.com publishes news and information for general informational and educational purposes. Information is compiled from sources believed to be reliable, but Vanderbiltreport.com does not guarantee the accuracy, completeness, or timeliness of all information presented. Readers should independently verify information and conduct their own research before making financial, investment, business, or other decisions.