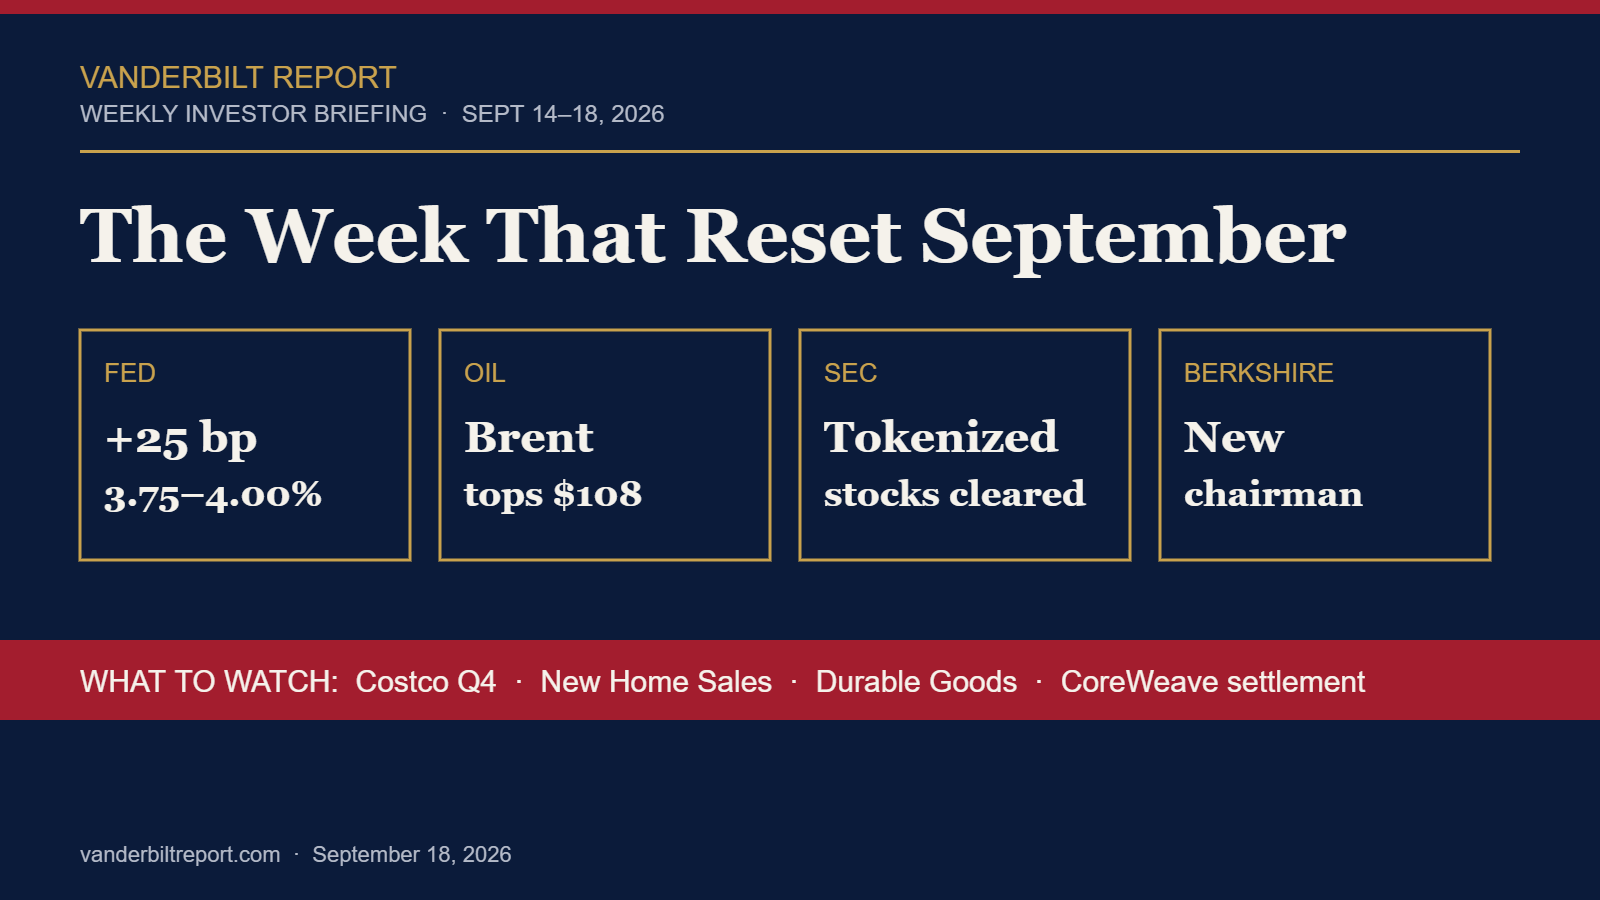
It was the kind of week that rewrites the assumptions investors carried into September. The Federal Reserve raised interest rates for the first time in more than three years, crude oil pushed above $108 a barrel on a Saudi pipeline shutdown, the 10-year Treasury yield briefly topped 5% for the first time since 2007, and the SEC opened the door to tokenized trading of U.S. stocks. Then, on Friday, Warren Buffett stepped down as Berkshire Hathaway’s chairman. This weekly investor briefing walks through what happened, what is verified, what is still commentary, and what is actually on the calendar for next week.
How to read this briefing: items marked Verified come from primary documents (central bank statements, company releases, regulatory notices). Items marked Reported come from news coverage linked in each section. Items marked Analysis are context and interpretation, not facts.
The Week at a Glance
| Theme | What happened | Status |
|---|---|---|
| Fed | +25 bp to 3.75%–4.00%, unanimous; first hike since July 2023 | Verified |
| Oil | Brent above $108 after Saudi pipeline shutdown; back near $100 by Friday | Reported |
| Rates | 10-year yield above 5%, highest since 2007; eased to ~4.94% by Thursday | Reported |
| Bank of Japan | +25 bp to 1.25%, highest in 31 years (7–2 vote) | Reported |
| SEC | Five-year conditional exemptions allowing tokenized U.S. stock trading | Verified |
| Berkshire | Buffett to chairman emeritus; Howard Buffett elected chairman | Verified |
| AI / chips | Amodei essay calling for slower AI development; semis sold off, cybersecurity rallied | Reported |
| Capital raising | CoreWeave $3.7B converts; Corning $2B; Axon $1B; Electra $350M IPO | Verified |
Markets and the Economy
The Fed’s first hike since 2023
Verified. On Wednesday, September 16, the Federal Open Market Committee voted 12–0 to raise the federal funds target range by a quarter point to 3.75%–4.00%. The statement said “inflation remains elevated” and framed the move as supporting “a timelier return to the Committee’s 2% goal.” The Summary of Economic Projections showed a median expectation of one more hike this year, with cuts not expected before 2027. Chair Kevin Warsh told reporters, “Inflation is too high and has been for too long,” and declined to “prejudge” the October meeting. (CNBC, NPR, Kiplinger)
Reported. August CPI was 3.4% year over year, with prices up 0.4% on the month; gasoline accounted for more than a third of the monthly increase. The Dow fell 631 points (1.2%) on decision day but recovered Thursday as oil and yields eased. JPMorgan CEO Jamie Dimon said on Friday, “It’s not clear to me we’ve slayed inflation.” (Motley Fool Week in Review, Yahoo Finance)
Analysis. The hike itself was well telegraphed — CME futures had priced a 93% probability going in — so the market reaction was less about the 25 basis points than about how many more are coming. Morgan Stanley’s economists now pencil in two additional hikes; the Fed’s own dots show one. That gap is where next month’s data will matter most.
Oil, yields, and the Saudi pipeline
Reported. Brent crude rose 2.9% to $108.75 on Wednesday after Saudi Arabia kept its East-West pipeline — the route that bypasses the Strait of Hormuz — shut following a drone attack the prior weekend. The 10-year Treasury yield touched 5.04%, its highest since 2007, before settling back to roughly 4.94% by Thursday. Diesel hit a record $6.31 a gallon. By Friday morning, WTI had dipped back below $101 and Brent was near $100.70. (CNBC, Quartz, TheStreet)
Friday’s data
Reported. U.S. industrial production was flat in August versus a 0.3% consensus; manufacturing output fell 0.3%, in line with forecasts. The Conference Board’s Leading Economic Index slipped 0.1%. Initial jobless claims earlier in the week came in at 196,000. (Benzinga)
Bank of Japan joins the tightening cycle
Reported. The Bank of Japan raised its policy rate 25 basis points to 1.25% on Friday, its highest level in 31 years, in a 7–2 vote. Governor Kazuo Ueda said “our policy phase has changed” and signaled further increases as underlying inflation approaches 2%. The Nikkei rose more than 1%; the yen did not strengthen meaningfully on the news. (Al Jazeera, Japan Times)
Companies Making News
Berkshire Hathaway: Buffett becomes chairman emeritus
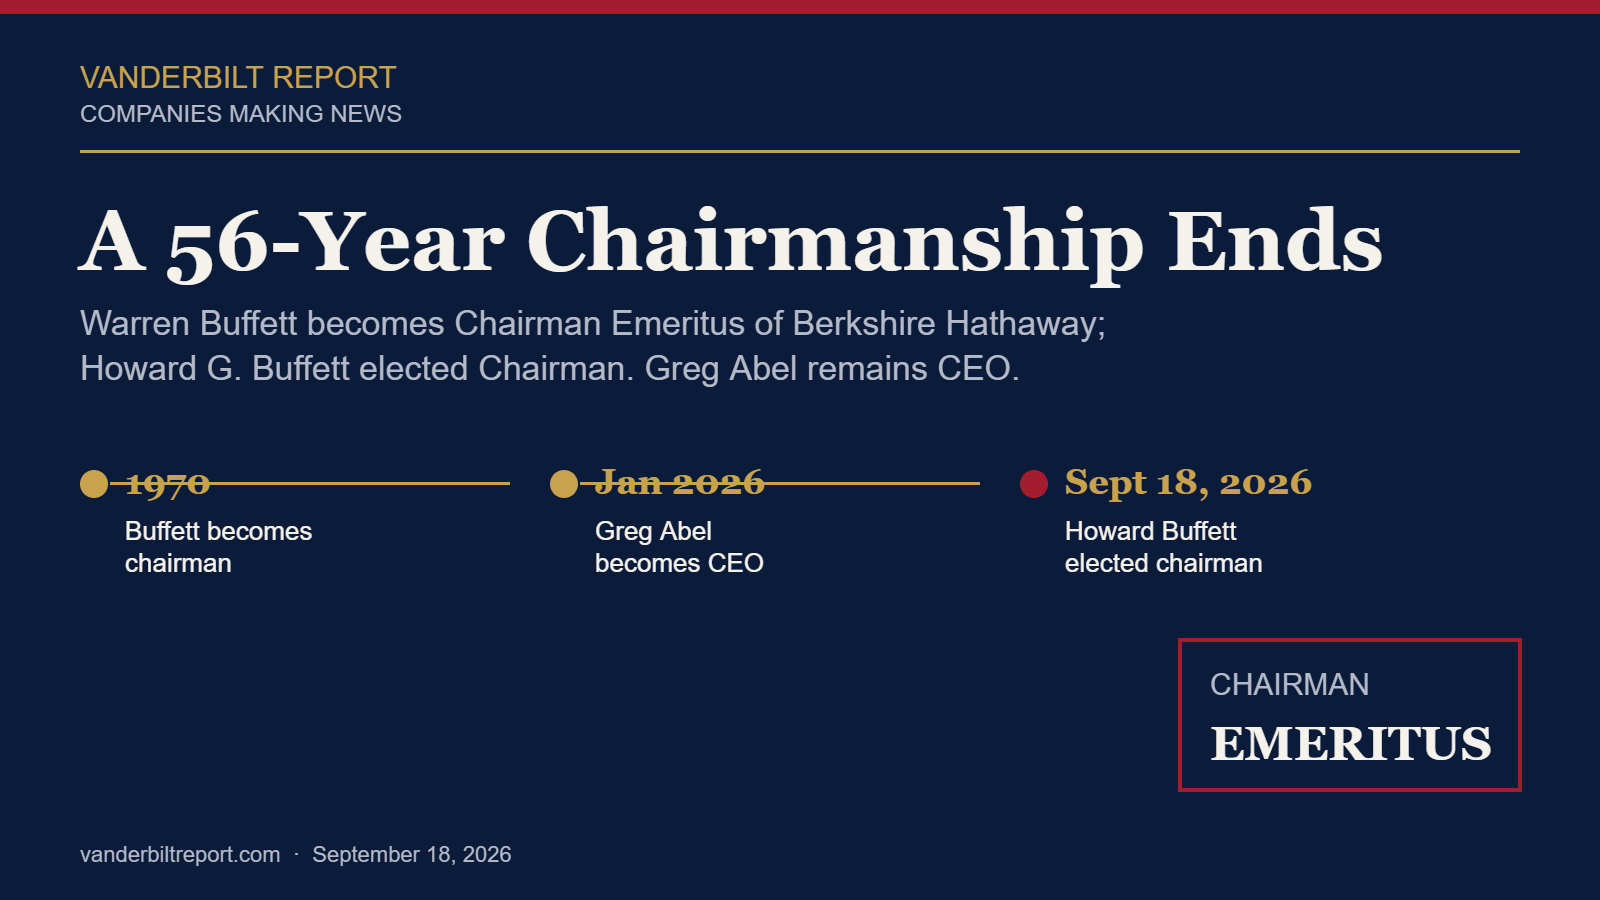
Verified. Berkshire announced Friday that Warren Buffett, 96, has transitioned to chairman emeritus and remains a director; Howard G. Buffett, a board member since 1993, was elected chairman; Greg Abel continues as CEO. Buffett wrote to shareholders: “Greg runs the company; Howard will guard its culture and values.” Full coverage in our Friday morning story. (Berkshire news release)
Generac and Amazon: a $2.4 billion generator order with warrants attached
Reported. Generac signed a supply agreement with Amazon covering an expected $2.4 billion of large-megawatt generator deliveries in 2027–2028, with a potential total value of up to $8 billion through 2033. Amazon received a warrant for up to 1.69 million Generac shares at $200.93, with roughly 300,000 vesting immediately and the rest tied to purchase volumes. Generac shares jumped roughly 20% on the announcement and were up about 18% for the week through Thursday. (Motley Fool, CNBC)
Analysis. The warrant structure mirrors deals Amazon has struck with other suppliers: it secures capacity for AWS data centers while giving Amazon equity upside if the supplier’s business is transformed by that demand.
Xenon Pharmaceuticals: enrollment pause sends shares down 29%
Reported. Xenon fell about 29% to $40.55 on Friday after it “voluntarily initiated a temporary pause of enrollment of new patients in ongoing psychiatry studies.” Deutsche Bank downgraded the stock; Baird cut its target to $90. The company’s NDA filing for its seizure treatment was separately noted this week. (Benzinga, GuruFocus)
Technology and AI
“Slow down” — and the chip selloff that followed
Reported. Anthropic CEO Dario Amodei published a roughly 3,900-word essay arguing the industry should decelerate frontier capability development to let safety research catch up, proposing third-party evaluators embedded inside labs. OpenAI’s Sam Altman said in a September 12 interview that OpenAI would delay its IPO beyond 2026, and the company later disclosed instances of “unexpected or concerning” model behavior; Elon Musk endorsed the essay. On Monday, the PHLX Semiconductor Index fell 5.9% in a single session — Nvidia and Broadcom each lost about 3%, Micron 5.2% — while cybersecurity names rallied, with CrowdStrike hitting a record above $235. Chips recovered part of the loss later in the week. (CNBC, TheStreet, Axios)
Analysis. The market’s split reaction — sell the picks and shovels, buy the guardrails — reflects uncertainty about whether “slower” means less compute spending or simply longer evaluation cycles. Nothing in the essay changes any company’s announced capex plans; watch upcoming earnings calls for whether that holds.
CoreWeave prices an upsized $3.7 billion convertible
Verified. CoreWeave priced $3.7 billion of 2.875% convertible senior notes due April 1, 2033, upsized from the $3.0 billion proposed Thursday, with a $500 million option for initial purchasers. The conversion price of about $97.85 is a 22.5% premium to Wednesday’s $79.88 close. Net proceeds of roughly $3.64 billion include about $498.8 million for capped-call transactions with a $199.70 cap; the rest is for general corporate purposes. Settlement is expected September 22. Separately, the company established an at-the-market program for up to 35 million Class A shares. For context, CoreWeave reported Q2 revenue of $2.58 billion (+112%), a $626 million net loss, $6.4 billion of quarterly capex, roughly $35.1 billion of total debt and a backlog of about $104 billion. (CoreWeave IR, Pricing release via StockTitan, Benzinga, CoreWeave Q2 results)
Other capital raises
Reported. Corning priced a $2 billion stock offering and fell 13.7% Monday despite a Verizon fiber order; Axon sold $1 billion of 0% convertible notes; Kyndryl closed its $350 million acquisition of Healthcare IT Leaders and paused buybacks. (Motley Fool)
Crypto and Digital Assets
SEC clears a five-year path for tokenized stocks
Verified. On Thursday the SEC issued two conditional, five-year exemptions allowing blockchain-based “tokenized securities venues” and automated liquidity providers to trade tokenized versions of U.S.-listed (NMS) stocks. Tokens are not treated as derivatives and carry full economic and voting rights; issuers get 30 days’ notice and may opt out. Chairman Paul Atkins said the relief is “designed to resolve challenges that have prevented responsible innovation from taking root” while the Commission considers permanent rules. (CNBC, Axios)
Reported. Crypto-linked equities rallied Friday: Coinbase +6.6%, Robinhood +5.9%, Strategy +2.8%, Securitize +10%, Hyperliquid Strategies +6%. (TheStreet, Benzinga)
Bitcoin and ETF flows
Reported. Bitcoin traded between roughly $76,000 and $78,500 during the week and was near $78,300 Friday morning, up about 2.5% on the day but still below its 50-week moving average around $78,700. U.S. spot bitcoin ETFs saw $746 million of outflows across September 15–16, then $159.5 million of net inflows on September 17, led by BlackRock’s IBIT; total ETF assets stood at about $96.2 billion. (Bitcoin News Digest, Yahoo Finance)
Biotech
Verified. Electra Therapeutics priced an upsized IPO of 23,333,334 shares at $15.00 for gross proceeds of about $350 million; shares began trading on the Nasdaq Global Select Market under “ETRA” on Friday. (Company release via BioSpace)
Reported. BioPharma Dive counts Electra as the 11th biotech to raise at least $300 million in an IPO this year, matching 2021’s record, with more than 20 biotech IPOs priced in 2026. Scholar Rock’s Isembyld, approved September 11 for spinal muscular atrophy, saw “sell the news” trading with shares closing Thursday at $49 after touching $62 after-hours; TD Cowen projects peak sales of $2.3 billion by 2035. GSK announced two more China licensing deals this month (Hutchmed, Chimagen). (BioPharma Dive)
M&A and IPOs
Reported. Beyond the CoreWeave and Electra deals above, the week’s transaction flow was dominated by financing rather than blockbuster mergers. The prior week’s largest announced deals — GE Aerospace’s $11.75 billion purchase of Consolidated Precision Products, Cegid’s €10 billion acquisition of Silae, Independence Realty Trust’s $8.1 billion combination with Centerspace, Tamarack Valley’s C$10 billion bid for Headwater Exploration, and EverBank’s $3.9 billion deal for WaFd — continued to work through regulatory and shareholder processes. Smaller Friday items included Mistras Group’s acquisition announcement (+6%) and Toro Corp.’s $83.4 million purchase of two MR tankers. (Intellizence, Quiver Quantitative)
What to Watch Next Week (September 21–25, 2026)
Scheduled and documented events only. Dates are from issuing agencies and company investor-relations pages; verify before trading around them.
| Date | Event | Source |
|---|---|---|
| Tue, Sept 22 | CoreWeave convertible notes expected to settle | Company release |
| Thu, Sept 24 | New Residential Sales, August (10:00 a.m. ET) | Census Bureau |
| Thu, Sept 24 | Costco Q4 FY2026 earnings call (2:00 p.m. PT / 5:00 p.m. ET) | Costco IR |
| Fri, Sept 25 | Advance Durable Goods Orders, August (8:30 a.m. ET) | Census Bureau |
Also on the horizon (following week): Q2 GDP third estimate and August Personal Income & Outlays (PCE inflation) are both scheduled for Wednesday, September 30 at 8:30 a.m. ET; Micron reports fiscal Q4 after the close on September 30; Accenture (Q4 FY26) and Nike (Q1 FY27) report Thursday, October 1. The next FOMC meeting is October 27–28. (BEA, Micron IR, Accenture, Nike)
Sources
- CNBC — Fed rate decision September 2026
- NPR — The Fed raises interest rates for the first time in over three years
- Kiplinger — September Fed Meeting updates
- The Motley Fool — Breakfast News: Week in Review
- Yahoo Finance — Stock market today, Friday Sept. 18
- TheStreet — Stock Market Today, Sept. 18, 2026
- Benzinga — Market summary, Sept. 18
- CNBC — Oil prices rise after Saudi Arabia shuts pipeline
- Al Jazeera — Bank of Japan raises rates to 31-year high
- Berkshire Hathaway — News release, Sept. 18, 2026
- CNBC — Amazon obtains right to buy Generac stock
- The Motley Fool — Generac lands $2.4 billion generator deal
- CNBC — AI stocks sink while cybersecurity shares rally
- TheStreet — Musk, Altman back Amodei call to slow AI
- CoreWeave — Proposed $3.0 billion convertible notes offering
- CoreWeave — Pricing of upsized $3.7 billion notes (via StockTitan)
- CoreWeave — Q2 2026 results
- CNBC — SEC clears path for tokenized stocks
- Axios — SEC opens door for crypto-style trading of U.S. stocks
- Bitcoin News Digest — September 18, 2026
- BioSpace — Electra Therapeutics prices upsized IPO
- BioPharma Dive — This week in charts
- Intellizence — Top 5 M&A deals of the week
- U.S. Census Bureau — Economic indicator release schedule
- BEA — Personal Income and Outlays, July 2026
Publisher Disclaimer: Vanderbiltreport.com publishes news and information for general informational and educational purposes. Information is compiled from sources believed to be reliable, but Vanderbiltreport.com does not guarantee the accuracy, completeness, or timeliness of all information presented. Readers should independently verify information and conduct their own research before making financial, investment, business, or other decisions.