Green Circle Decarbonize Technology Limited (NYSE American: GCDT) is a small Hong Kong company built around one idea: store “coolness” in phase change material (PCM) so buildings run their air-conditioning plants more efficiently. It listed in January 2026, raised US$11.5 million in gross proceeds, and has since signed a financing package and a share consolidation that change the picture for anyone looking at Green Circle Decarbonize Technology stock today.
This profile covers what the company does, the market it sells into, how it compares with much larger players, what its filings show, and the risks it discloses.
Why investors are watching Green Circle Decarbonize Technology stock now
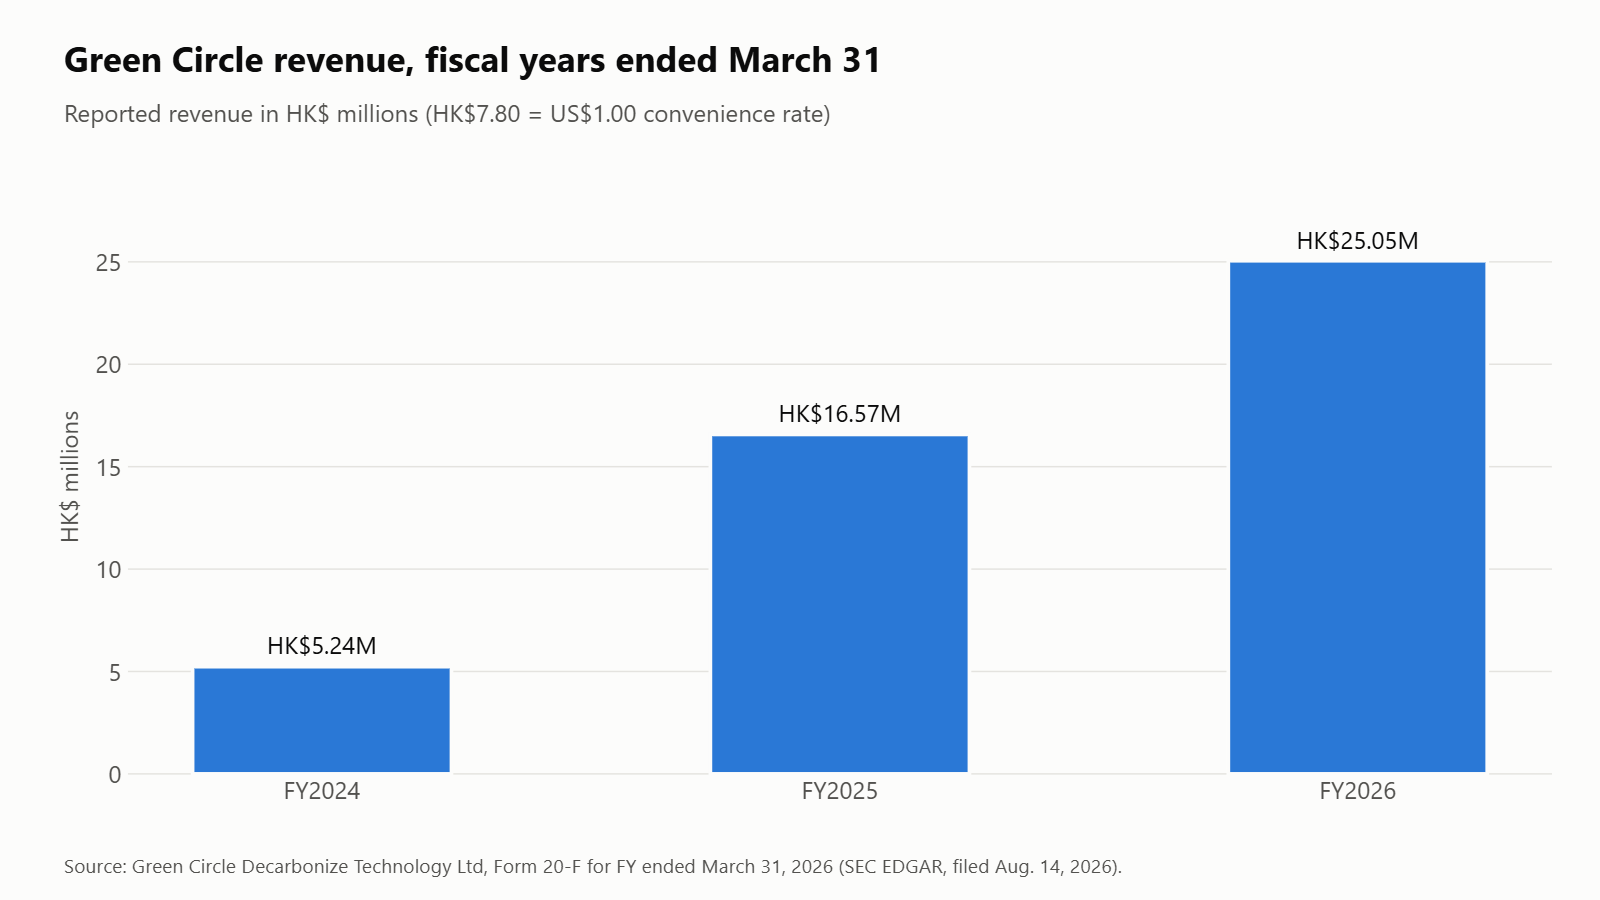
- Revenue grew 51.1% to HK$25.1 million (about US$3.2 million) in the fiscal year ended March 31, 2026. [Verified]
- A 1-for-6 share consolidation takes effect October 7, 2026, which the company says is aimed at raising the per-share price and maintaining NYSE American compliance.
- A July 2026 financing added a US$10 million note, 29.1 million warrants and a US$100 million equity purchase facility, creating significant potential dilution.
- New tender proposals with Nan Fung Property Management were announced September 30, 2026; neither has been awarded.
GCDT at a glance
| Listing | NYSE American: GCDT (Class A ordinary shares); IPO priced at US$4.00 on January 12, 2026; trading began January 13, 2026 |
| Incorporation / operations | Cayman Islands holding company; operates through Boca International Limited in Hong Kong |
| Fiscal year-end | March 31 |
| Latest annual revenue | HK$25,051,359 (about US$3.21 million), FY ended March 31, 2026 |
| Net loss | HK$13,113,273 (about US$1.68 million), FY2026 |
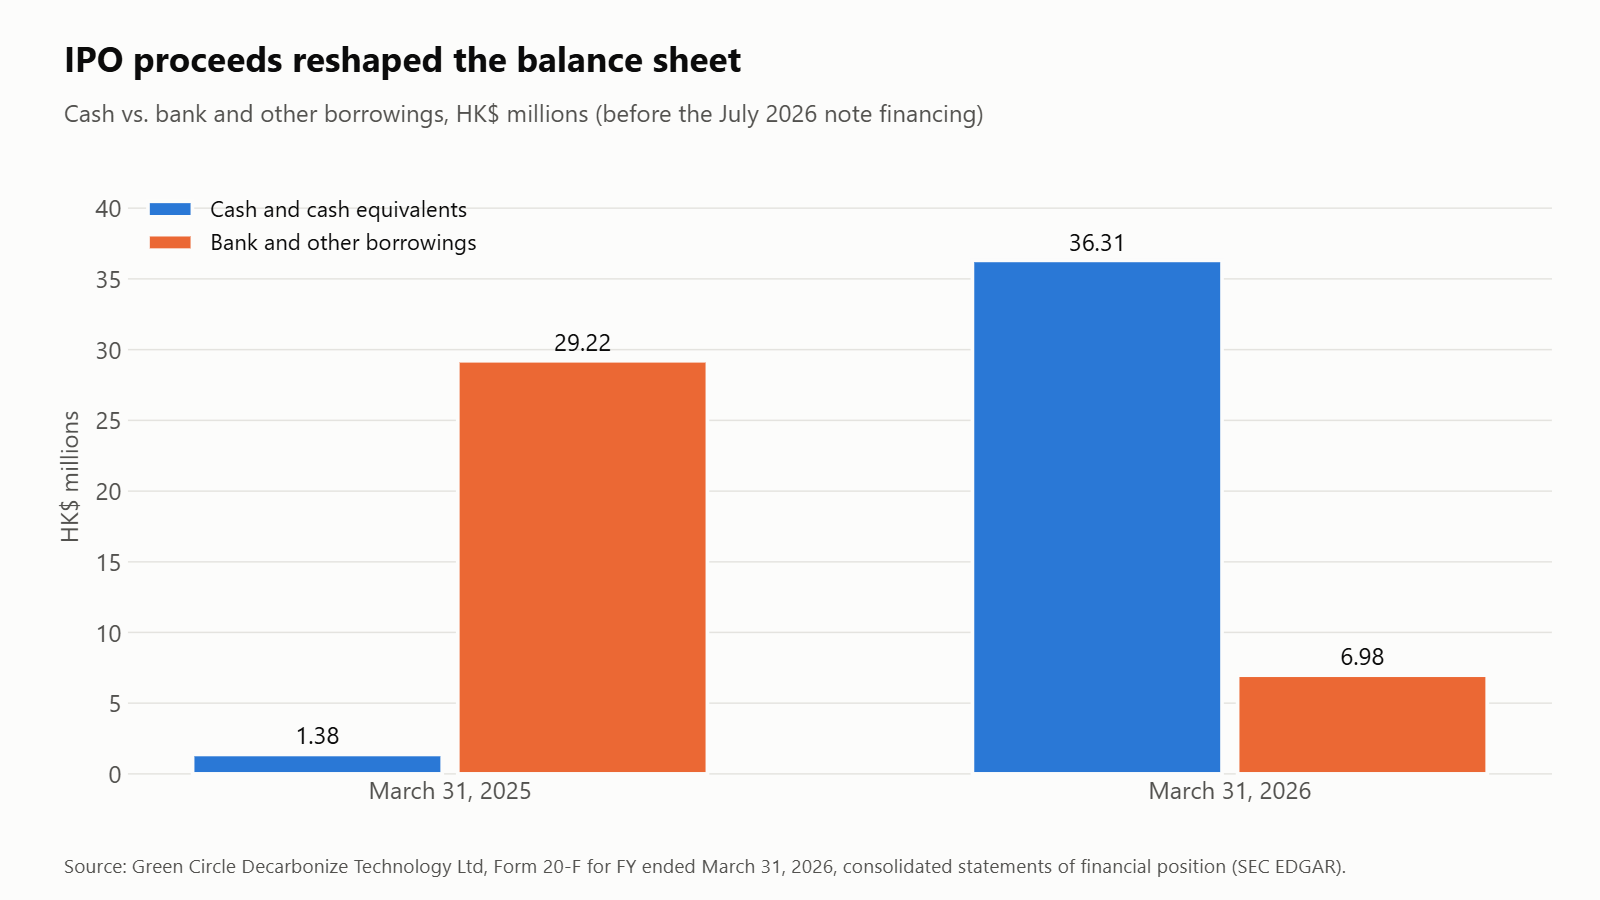
| Cash | HK$36,308,320 (about US$4.66 million) at March 31, 2026 |
| Bank and other borrowings | HK$6,978,895 (about US$0.89 million) at March 31, 2026, before the July 2026 note |
| Shares outstanding | 12,875,000 ordinary shares at March 31, 2026, before later issuances and the 1-for-6 consolidation |
| Employees | 4, all in Hong Kong, at March 31, 2026 |
| Recent share price | US$0.40 at the October 2, 2026 close (pre-consolidation), per StockAnalysis; 52-week range US$0.3302 to US$5.85 |
| Next key dates | October 7, 2026: 1-for-6 consolidation effective; January 16, 2027: maturity of the US$10 million note |
Business overview: phase change material for building cooling
- Green Circle makes PCM thermal energy storage (PCM-TES) products and designs high-efficiency chiller plants around them.
- Its main pitch is a performance-based contract: the customer pays nothing up front and instead pays from the energy cost it saves.
- Construction work made up most of FY2026 revenue, at close to zero gross margin on two projects. [Verified]
What the company sells
Phase change materials absorb and release large amounts of heat as they freeze and melt. Green Circle says it began operating in 1992, when it established Boca International Limited, and that one of its key materials changes phase at +8°C, a temperature suited to chilled-water air-conditioning.
Its flagship offering is the “Ultra-High Efficiency Boca Hybrid Power Chiller Plant,” which combines chillers, cooling towers, BocaPCM-TES storage and BocaAI controls. Storage lets a building shift cooling load from peak to off-peak tariff periods. The company has applied for patents on the chiller plant in the United States and the PRC. [Verified] Using its HAECO project as a reference, it says installations can cut electricity use by at least 40% and running costs by about 50% to 70%, depending on local tariffs.
The company website also lists PCM panels, PCM-TES tanks and a PE-50 panel for -50°C cold storage. It names MTR, Sun Hung Kai Properties, the University of Hong Kong and IBM among past clients.
How it makes money
The 20-F describes two models. Under performance-based contracting, Green Circle funds and installs the plant and charges a share of the electricity saved. The HAECO project uses this model, and it produces recurring but seasonal revenue that falls when cooling demand drops. Under a build-and-sell model, it builds the plant and sells it to the client.
| Revenue by service (HK$) | FY2026 | FY2025 | FY2024 |
|---|---|---|---|
| Energy saving services | 7,887,455 (31.5%) | 5,077,844 (30.6%) | 5,236,437 (100%) |
| Construction service | 17,163,904 (68.5%) | 8,497,077 (51.3%) | – |
| Consultancy service | – | 3,000,000 (18.1%) | – |
| Total | 25,051,359 | 16,574,921 | 5,236,437 |
Customers
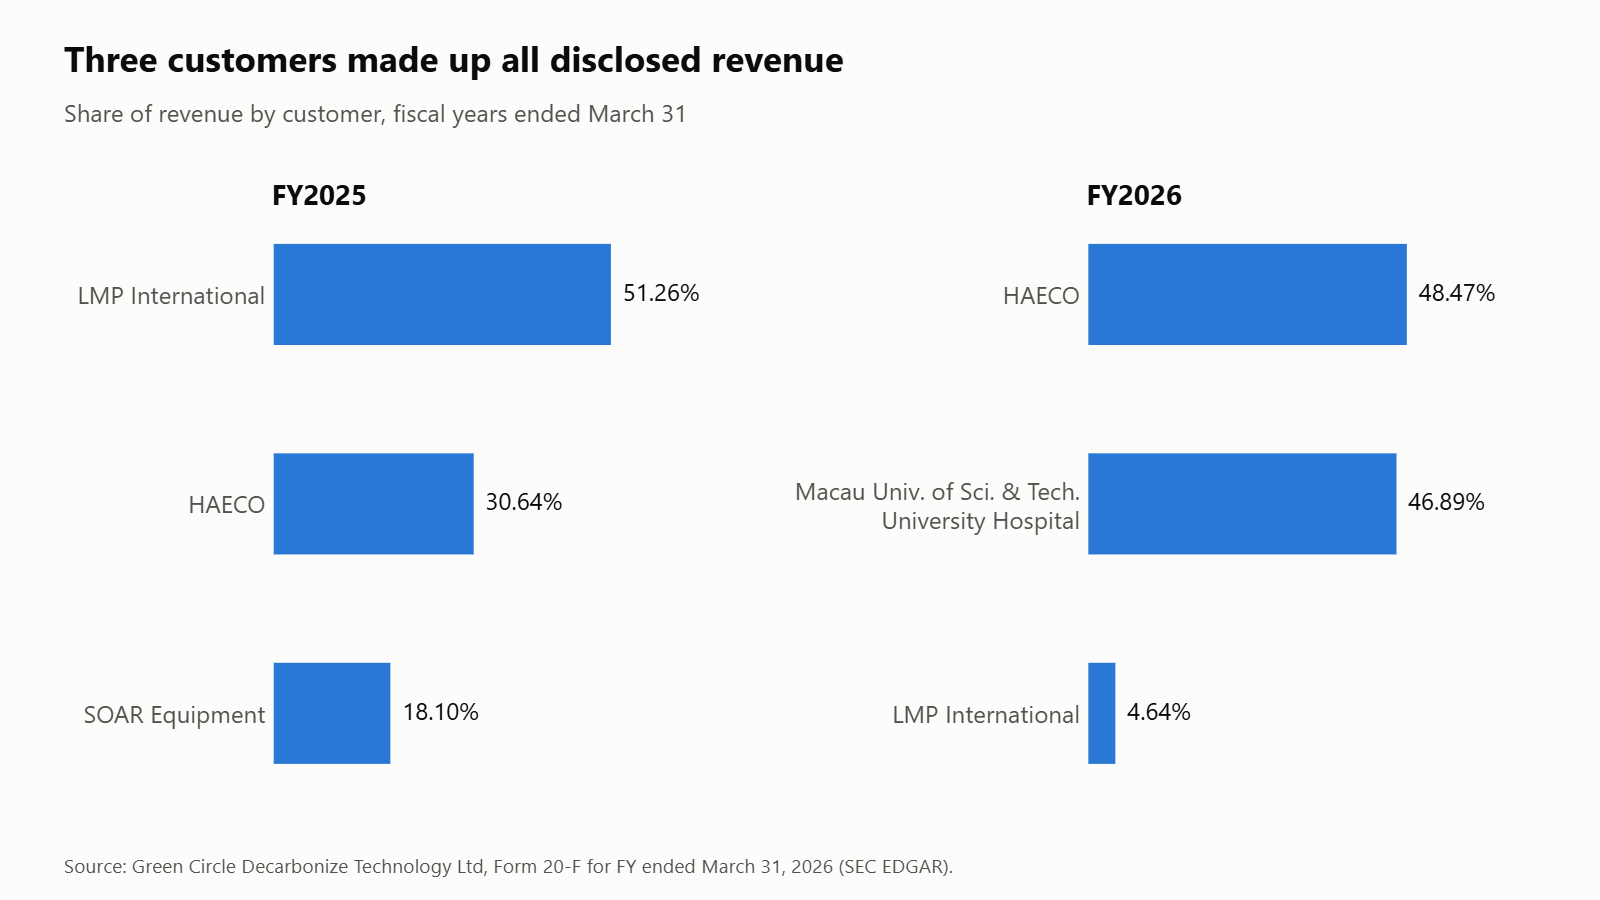
Three customers accounted for all of FY2026 revenue: HAECO (Hong Kong Aircraft Engineering Company) at 48.47%, Macau University of Science and Technology Foundation – University Hospital at 46.89%, and LMP International Limited at 4.64%. The Macau hospital chiller plant project was completed in May 2026.
Leadership
Founder Chan Kam Biu Richard is Chief Executive Officer and a director. The 20-F says he oversees R&D, sales, product design, plant construction, PCM production and quality control. Lui Lai Yuen is Chief Administrative Officer and a director. Louis Ho Ming Leung became Chief Financial Officer on June 8, 2026, after former CFO Lai Tai Yan resigned effective April 15, 2026.
Recent catalysts: financing, dual-class shares and a consolidation
- The July 2026 package gives Green Circle access to capital, but on terms that can heavily dilute existing holders.
- A new dual-class structure gives the founder’s holding entities 50 votes per share.
- The 1-for-6 consolidation on October 7, 2026 resets the share count and price; it does not change the company’s value.
July 2026 note, warrants and US$100 million equity facility
On July 16, 2026, Green Circle signed a securities purchase agreement with Target Capital 1, LLC. [Verified] The terms in its 6-K and Form F-1 include:
- An unsecured promissory note with US$10.0 million principal and a US$8.0 million subscription price (a 20% original issue discount), maturing January 16, 2027. It carries 0% interest unless it defaults, when the rate becomes 20%.
- The note converts at the greater of US$0.1099 or 80% of the lowest closing price in the prior five trading days.
- 29,122,679 warrants exercisable at US$2.00 through July 16, 2028, plus 1,143,962 pre-funded warrants.
- An equity purchase agreement for up to US$100.0 million of Class A shares over 12 months (extendable), with a US$2.0 million commitment fee payable in shares.
- The first closing on July 24, 2026 funded US$2.0 million in gross proceeds. Revere Securities LLC acted as placement agent.
The September 21, 2026 Form F-1 registers up to 182,016,746 Class A shares issuable on note conversion and up to 264,987,889 Class A shares underlying warrants for resale, both on a pre-consolidation basis. Either figure is many times the 12,875,000 shares outstanding at March 31, 2026.
Dual-class reclassification
Shareholders approved a reclassification on August 10, 2026, effective August 14, 2026. Class A shares carry one vote and Class B shares carry 50 votes. Joyful Star Limited (5,280,000) and Green Circle Limited (1,080,000) converted their holdings into 6,360,000 Class B shares, which carry 318,000,000 votes in total. The 20-F puts the CEO’s beneficial ownership at about 46.93%.
1-for-6 share consolidation
Announced September 23, 2026, the consolidation takes effect at 12:01 a.m. Eastern Time on October 7, 2026, under the new CUSIP G4092C131. Par value rises from US$0.001 to US$0.006, and fractional entitlements are rounded up. The company said the goal is to raise the per-share trading price and maintain compliance with NYSE American listing standards. For background on how consolidations work, see our explainer, Reverse Stock Splits Explained.
Market analysis: buildings, cooling and phase change materials
- In Hong Kong, buildings account for about 90% of electricity use.
- Published estimates of the global PCM market vary widely, from under US$1 billion to US$2.6 billion for 2024–2025.
- Green Circle’s 20-F cites no third-party market-size figures of its own.
Green Circle’s home market sits on a clear demand driver. Hong Kong’s Council for Sustainable Development says buildings account for about 90% of the city’s electricity consumption, and that generating that electricity produces over 50% of the city’s carbon emissions. [Third-party] The 20-F also names government incentives, including Hong Kong’s Energy Efficiency Registration Scheme for Buildings, as demand drivers. It adds that market acceptance of energy-saving services is “not certain.”
Third-party sizing of the global PCM market depends heavily on scope:
- MarketsandMarkets: US$729.76 million in 2025, forecast at US$1,639.71 million by 2030, a 17.58% CAGR.
- Global Market Insights (Nov. 2025): US$2.6 billion in 2024, forecast at US$7.9 billion by 2034, an 11.4% CAGR. Asia Pacific was the largest region at US$1.1 billion, and construction and buildings was the top application at 28% (US$742 million).
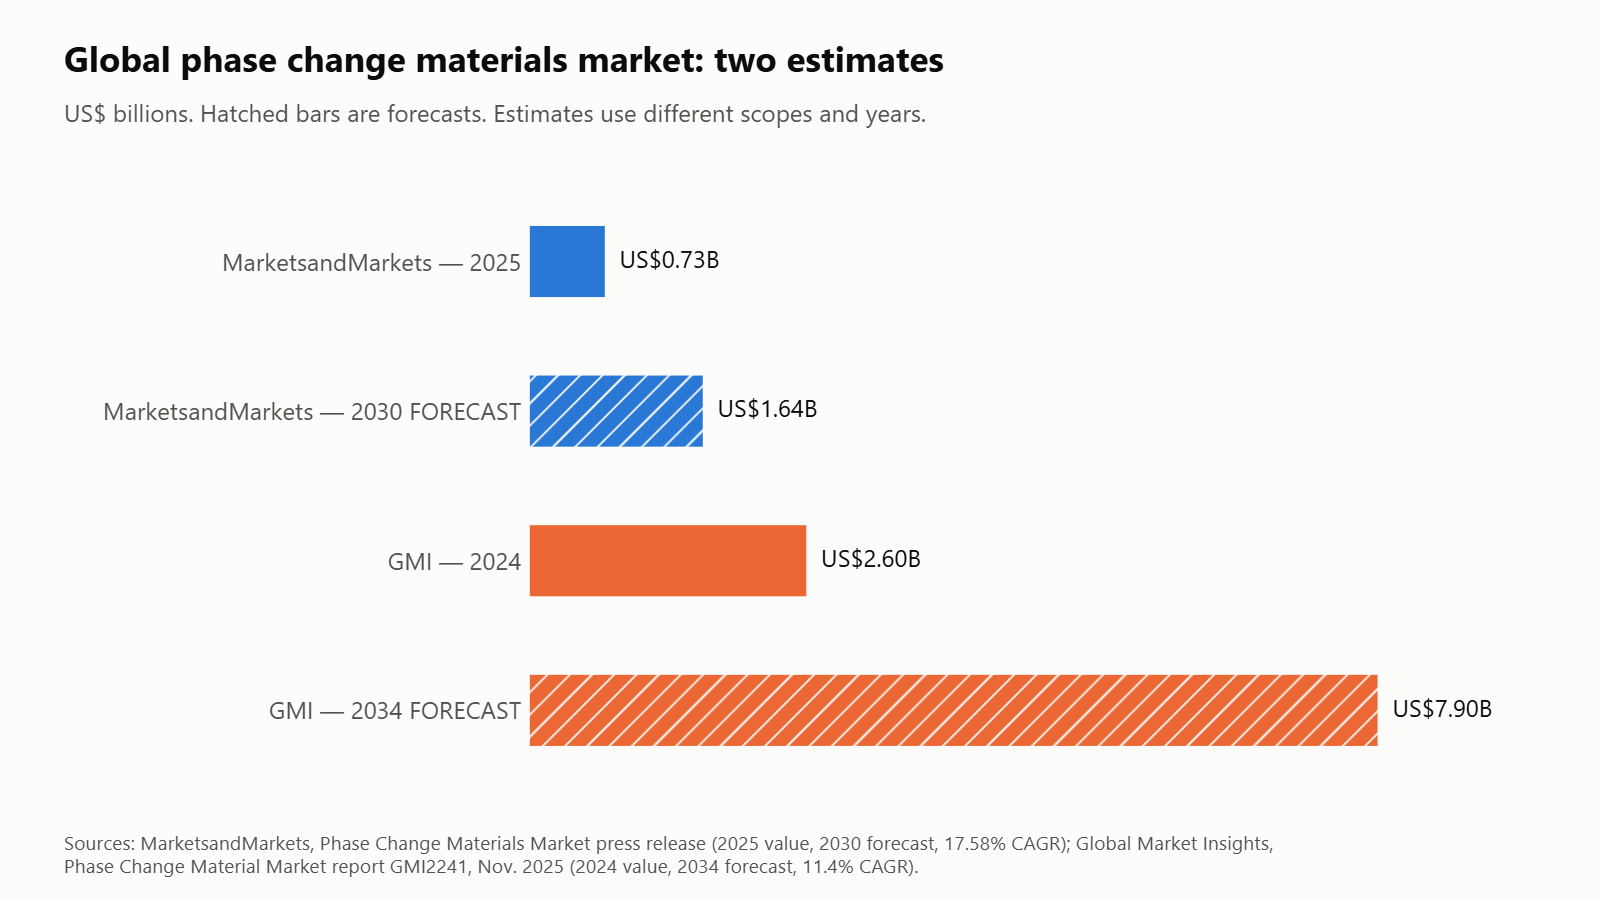
These figures cover PCM materials across all uses, including electronics, textiles and cold chain, not just building cooling. Green Circle’s addressable slice is a much smaller part of either total.
Competitive analysis
- Green Circle competes with global chemical companies on PCM materials and with HVAC majors on thermal storage.
- The 20-F names no specific competitors and warns that rivals “may have superior financial and technical resources.”
- Its differentiators are a vertically integrated product and the performance-based contract model.
| Company | Relevance to Green Circle | Source |
|---|---|---|
| BASF SE | Ranked as the PCM market leader, with about 7% share in 2024 | Global Market Insights |
| Honeywell, Croda, Rubitherm, Henkel | Among the top five PCM suppliers by share | Global Market Insights |
| DuPont, Boyd, Sasol, PureTemp, Outlast | Named key PCM market players | MarketsandMarkets |
| Trane (CALMAC) | Ice-based cool energy storage for buildings; Trane acquired CALMAC in November 2017 | Utility Dive |
| Green Circle (GCDT) | Proprietary +8°C PCM, integrated chiller plant with PCM-TES and AI controls, offered under performance-based contracts | Form 20-F |
With four employees and US$3.2 million of revenue, Green Circle is a niche specialist next to these companies. Any edge has to come from project results and its financing model rather than scale.
Financial snapshot and outlook
- Revenue rose 51.1% in FY2026, but gross margin fell to 17.3% from 22.6%.
- The net loss widened to HK$13.1 million, including a one-time loss on settling debt with shares and higher IPO-related professional fees.
- IPO cash cut borrowings and turned shareholders’ equity positive.
| HK$ (FY ended March 31) | FY2026 | FY2025 | FY2024 |
|---|---|---|---|
| Revenue | 25,051,359 | 16,574,921 | 5,236,436 |
| Gross profit | 4,345,233 | 3,751,406 | 1,445,134 |
| Gross margin | 17.3% | 22.6% | 27.6% |
| Administrative expenses | (11,178,915) | (7,668,127) | (7,102,218) |
| Finance costs | (576,362) | (2,445,201) | (2,512,023) |
| Other income / (losses) | (5,703,229) | 379,702 | 247,167 |
| Net loss | (13,113,273) | (5,982,220) | (7,921,940) |
| Loss per share (basic) | (1.24) | (0.60) | (0.86) |
| Net cash from operating activities | (15,523,724) | 5,045,485 | 1,359,309 |
What drove the numbers
The company attributes the margin decline to a larger share of construction revenue. On two construction projects, it recognized revenue only to the extent of costs incurred because it could not reasonably measure progress, leaving those projects at close to zero gross margin. Administrative expenses rose by about HK$3.5 million, mainly from IPO-related professional fees.
The wider loss also includes a one-time loss on extinguishing financial liabilities through issuing 600,000 ordinary shares to two borrowers. The cash flow statement shows a HK$12.43 million loss on extinguishment, partly offset by HK$6.51 million of waived interest. Both are largely non-cash. [Verified] [Analysis] Operating cash outflow of HK$15.5 million reflects lower payables, the release of HK$4.67 million of contract liabilities and higher receivables.
Balance sheet
The IPO and over-allotment raised US$11.5 million gross: 2,500,000 shares on January 14, 2026 and 375,000 on February 12, 2026, both at US$4.00. [Verified] By March 31, 2026, cash had risen to HK$36.3 million from HK$1.4 million, and borrowings had fallen to HK$7.0 million from HK$29.2 million after HK$15.1 million of principal repayments. Equity moved to HK$54.5 million from a deficit of HK$21.0 million. [Verified] Capital spending on property, plant and equipment was HK$8.6 million.
The financial statements are prepared on a going-concern basis. The 20-F notes that shareholders have agreed to provide funds so the group can meet its obligations as they fall due, and the company says it has sufficient funds for the next 12 months while cautioning that its assumptions “may prove to be wrong.”
Outlook
Green Circle has not issued numeric revenue or earnings guidance, and we found no named analyst estimates. This page therefore includes no forward financial figures.
Growth drivers
- Building-efficiency policy in Hong Kong and recurring savings-share contracts support demand. [Company statement]
- New tenders and expansion outside Hong Kong would broaden a very concentrated customer base. [Company statement]
- Expansion depends on financing that is now available but dilutive.
- New tenders: On September 30, 2026, Boca International said it submitted proposals to Nan Fung Property Management for a chiller replacement at MOS Centre (HK$7 million) and an HVAC retrofit and maintenance contract at Nan Fung Centre (HK$60 million). Neither has been awarded. [Company statement] [Developing]
- Capacity and reach: The 20-F lists factory construction and production machinery, local agents in markets outside Hong Kong, continued R&D, and possible acquisitions or licensing as growth strategies. [Company statement]
- Recurring contracts: Performance-based projects such as HAECO generate ongoing savings-share revenue once installed.
- Completed reference sites: The Macau University Hospital chiller plant, completed in May 2026, adds a hospital reference project.
Risks and considerations
- Dilution from the note, warrants and equity facility is the most immediate risk for shareholders.
- The business is very small and depends on a handful of customers and one founder.
- Hong Kong operations carry PRC regulatory and audit-inspection risks.
- Heavy potential dilution: The note converts at up to a 20% discount to recent prices, with a US$0.1099 floor on a pre-consolidation basis. Combined with 29.1 million warrants and a US$100 million equity line, shares registered for resale far exceed the existing share count.
- Share price and listing: The shares traded as low as US$0.3302 against a US$4.00 IPO price. The company has turned to a consolidation to maintain NYSE American compliance.
- Customer concentration: Three customers made up 100% of FY2026 revenue, and the mix changed sharply from FY2025.
- Losses and margins: The company has a history of net losses, an accumulated deficit of HK$50.5 million, and a falling gross margin.
- Financing model: Performance-based contracts need significant up-front funding, and the company warns there is “no assurance” it can keep obtaining it.
- Key person and small team: The company has four employees and relies heavily on its CEO. It replaced its CFO in 2026, and the 20-F says management lacks public-company experience.
- Control and governance: Class B shares carry 50 votes each, which concentrates voting control and may conflict with minority holders’ interests.
- Supply chain: A key nanomaterial comes from a single German supplier, with no long-term agreement.
- Hong Kong and PRC: The company discloses risks from possible PRC oversight of overseas offerings, CSRC filing rules, Hong Kong’s legal environment, and delisting under the Holding Foreign Companies Accountable Act if the PCAOB cannot inspect its auditor.
- Competition and IP: Rivals may have greater resources, and protecting patents and trademarks can be costly.
The bottom line
Green Circle Decarbonize Technology has a real product in a policy-supported niche. It has reference projects with an aircraft engineering group and a university hospital, more than three decades of work on its own phase change material, and revenue that has grown for two straight years. The IPO repaired a balance sheet that had negative equity.
It is also a four-person, loss-making company with three customers. Its July 2026 financing could multiply the share count, and voting control now sits firmly with the founder’s entities. For anyone researching GCDT stock, the questions are whether new contracts arrive fast enough, and on good enough margins, to outweigh dilution.
Milestones to watch:
- Trading on a split-adjusted basis from October 7, 2026
- Outcome of the Nan Fung tenders
- Note conversions and draws on the equity facility
- Effectiveness of the F-1 resale registration
- Any interim results for the six months ending September 30, 2026
- The note’s January 16, 2027 maturity
References
- Green Circle Decarbonize Technology Ltd, Annual Report on Form 20-F for the fiscal year ended March 31, 2026 (filed Aug. 14, 2026), SEC EDGAR
- Green Circle Decarbonize Technology Ltd, Registration Statement on Form F-1 (Sept. 2026), SEC EDGAR
- Green Circle Decarbonize Technology Ltd, Form 6-K on the July 2026 securities purchase agreement, SEC EDGAR
- “Green Circle Decarbonize Technology Limited Prices $10,000,000 Initial Public Offering,” press release, Jan. 12, 2026
- “Green Circle Decarbonize Technology Limited Announce Share Capital Increase and Share Capital Alteration,” GlobeNewswire, Aug. 18, 2026
- “Green Circle Decarbonize Technology Limited Announces 1-for-6 Share Consolidation Effective October 7, 2026,” Sept. 23, 2026 (via Stock Titan)
- “Green Circle Decarbonize Technology Limited Submits Tender Proposals,” Sept. 30, 2026 (via Stock Titan)
- BocaPCM / Boca International Limited company website
- StockAnalysis, GCDT quote and profile (price as of Oct. 2, 2026 close)
- MarketsandMarkets, Phase Change Materials Market press release
- Global Market Insights, Phase Change Material Market report (GMI2241, Nov. 2025)
- Council for Sustainable Development (Hong Kong), “Energy Saving and Green Buildings”
- Utility Dive, “Heating and AC company acquires ice energy storage company CALMAC,” Nov. 2017
Compensation Disclosure: Vanderbiltreport.com is owned by a US-based corporation. We have received compensation of up to $100,000 for profiling the company. Vanderbiltreport.com was not paid by Green Circle Decarbonize Technology Limited.
Publisher Disclaimer: Vanderbiltreport.com publishes news and information for general informational and educational purposes. Information is compiled from sources believed to be reliable, but Vanderbiltreport.com does not guarantee the accuracy, completeness, or timeliness of all information presented. Readers should independently verify information and conduct their own research before making financial, investment, business, or other decisions.